Construction financing involves more than a standard mortgage application. A lender needs to understand your finances, the project’s costs, who will do the work, and how the finished property will be completed. Requirements vary by lender, loan type, and project, so use this list as a preparation guide rather than a final checklist. Gathering documents early can help reveal missing details before underwriting begins and make it easier to respond when the lender asks for updates.
Borrower Financial Documents
Expect to provide identification and a completed loan application, along with documents that verify income and assets. Depending on how you earn income, these may include recent pay stubs, tax returns, W-2s, or business returns. Lenders may also request bank and investment account statements to confirm available funds for the down payment, closing costs, reserves, or construction expenses.
Prepare a list of monthly debts, including credit cards, auto loans, student loans, and other mortgages. If you own other properties or have additional income, gather records that support those details. Keep statements complete and legible, and avoid moving large sums between accounts without keeping a clear record of where the money came from.
Budget and Funding Details
A detailed project budget helps the lender assess whether the planned work is financially realistic. Include the land cost or current land value, site preparation, permits, labor, materials, professional fees, insurance, and other expected expenses. Separate costs by category and identify which items are estimates and which are based on signed agreements or written bids.
Lenders may ask how you will cover the required borrower contribution and any costs that exceed the approved loan amount. Provide evidence of funds and explain any other funding sources. Include a contingency allowance in the project budget where appropriate, and make sure the total agrees with the figures in your construction contract and draw schedule.
Contractor and Project Records
Gather the contractor’s signed construction agreement, scope of work, cost breakdown, and proposed timeline. The lender may also request licensing, insurance, and experience information. Confirm that the agreement identifies the parties, describes the work, states the contract amount, and explains how changes to the scope or price will be handled.
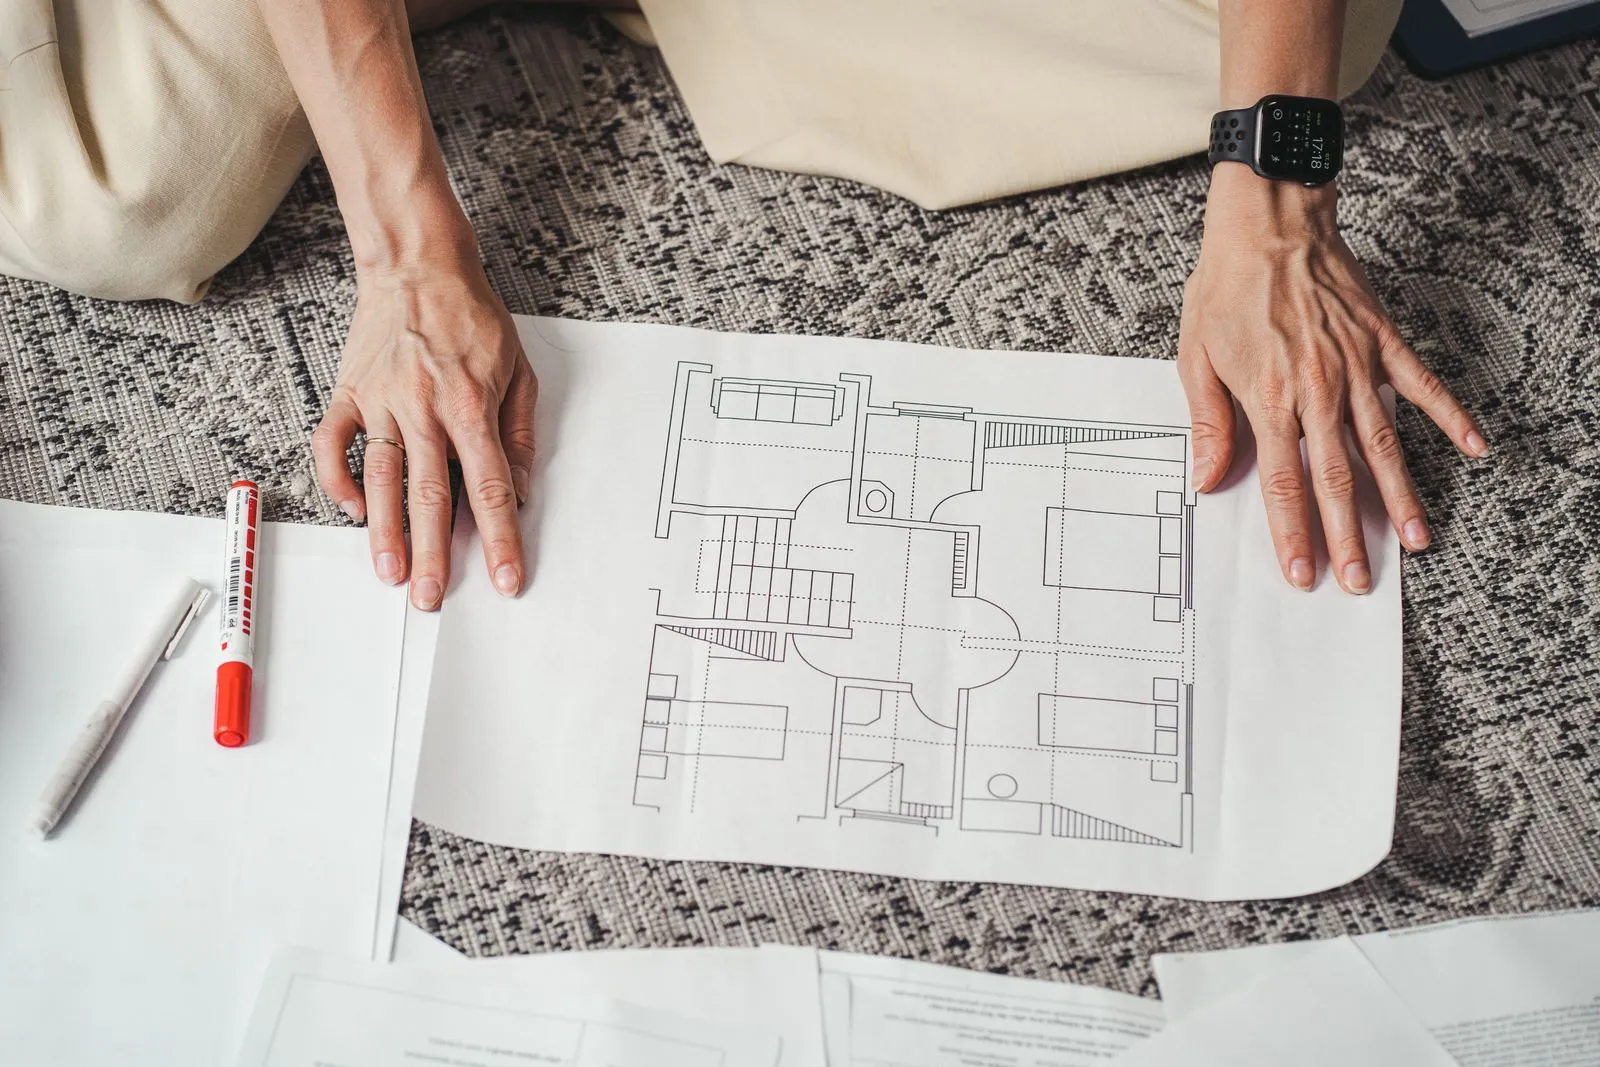
For the property and design, prepare the purchase contract or proof of ownership, plans, specifications, survey, and site information if available. Lenders may request permits, zoning details, engineering reports, or other approvals relevant to the project. They may also require an appraisal based on the completed plans, so keep the plans and specifications consistent with the budget and contractor documents.
Organize Before Applying
Create separate digital folders for borrower finances, budget, contractor records, and project documents. Use clear file names that include the document type and date, and keep a current version of each plan, estimate, and contract. Check that scans show every page and that names, addresses, and project totals match across the file.
Ask the lender for its current document checklist before paying for reports or ordering final plans. Requirements can change based on the loan program, property, and construction stage. GulfBuild Lending can help borrowers in St. Petersburg understand which records to assemble and identify questions to raise with a lender.
A well-organized file gives the lender a clearer view of your finances and construction plan. Start with the core records, then confirm project-specific requirements before submitting your application. If you are preparing for a build in St. Petersburg, contact a construction loan professional to discuss the documents your financing may require.